Animal Disinfectants Market 2031: Growth Trends, Market Opportunities & Industry Outlook

marketsandmarkets logo

The global animal disinfectants market is estimated to be valued at USD 4.51 billion in 2026 and is projected to reach USD 6.69 billion by 2031, registering a CAGR of 8.2% during the forecast period from 2026 to 2031. The market is witnessing steady growth as livestock, poultry, and aquaculture producers increasingly prioritize animal health, disease prevention, farm hygiene, and biosecurity.

Animal disinfectants play a critical role in controlling bacteria, viruses, fungi, and other microorganisms across animal production environments. Unlike routine animal cleaning products, disinfectants are specifically formulated to reduce pathogen loads in animal housing, equipment, milking systems, transportation facilities, veterinary facilities, and other production areas. The increasing incidence of infectious diseases, expansion of intensive animal farming, and growing global demand for animal protein are driving the need for effective and reliable disinfection solutions.

Animal disinfectants are available in various formulations, including liquids, powders, foams, and concentrates, catering to diverse applications across livestock housing, poultry farms, dairy operations, veterinary facilities, and other animal-care environments. The growing adoption of preventive biosecurity measures, stricter hygiene requirements, and increasing awareness of pathogen control are expected to further support market expansion.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=38718363

Livestock Segment to Dominate the Animal Disinfectants Market

By animal type, the livestock segment is expected to dominate the animal disinfectants market during the forecast period. The segment’s leading position can be attributed to the large-scale production of cattle, swine, and other farm animals and the extensive use of disinfectants across animal housing, farm premises, equipment, and transportation facilities.

The increasing emphasis on disease prevention, animal health, and biosecurity in livestock production is encouraging farmers and producers to adopt disinfection solutions as part of routine farm-management practices. As intensive livestock farming expands, maintaining hygienic production environments is becoming increasingly important for reducing the risk of disease transmission and supporting animal productivity.

Liquid Formulations to Account for the Largest Market Share

By form, the liquid segment is expected to hold the largest share of the animal disinfectants market during the forecast period. Liquid disinfectants offer versatility, ease of dilution, and compatibility with multiple application methods, including spraying, foaming, and surface disinfection.

Their widespread use across animal housing, farm equipment, milking systems, and other agricultural environments has contributed to their broad adoption. The convenience and adaptability of liquid formulations are expected to continue supporting their leading position in the market.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=38718363

Asia Pacific to Register the Fastest Market Growth

Asia Pacific is expected to be the fastest-growing region in the animal disinfectants market during the forecast period. The region’s growth is being driven by expanding livestock and poultry production, rising consumption of animal protein, and increasing adoption of farm biosecurity practices.

Recurring outbreaks of infectious diseases, including African swine fever and avian influenza, are encouraging producers and authorities to strengthen sanitation, hygiene, and disease-control measures. These developments are creating significant growth opportunities for manufacturers of animal disinfectants as producers seek effective solutions to minimize pathogen transmission and maintain healthier production environments.

Leading Animal Disinfectants Companies:

The animal disinfectants market features the presence of several established global players competing through product development, innovation, geographic expansion, and strategic initiatives. Key companies profiled in the market include LANXESS (Germany), Kersia Group (France), Ecolab (US), GEA Group Aktiengesellschaft (Germany), Solvay (Belgium), and Virbac (France), among others.

As animal production systems continue to evolve and biosecurity becomes an increasingly important component of modern farming, demand for effective animal disinfection solutions is expected to remain strong. Rising disease-management requirements, expanding intensive farming operations, and increasing awareness of animal health and farm hygiene are likely to create new opportunities for market participants through 2031.
Nematicides Market Research: Key Trends, Challenges, and Growth Opportunities

marketsandmarkets logo

The global nematicides market is projected to grow from USD 3.36 billion in 2026 to USD 5.60 billion by 2031, registering a CAGR of 10.7% during the forecast period. The market is witnessing significant growth as farmers increasingly seek effective solutions to combat crop losses caused by plant-parasitic nematodes and improve agricultural productivity on limited arable land.

The rising cultivation of high-value crops, including fruits, vegetables, and plantation crops, is further fueling demand for nematicides. Advances in seed-applied treatments, precision agriculture, and integrated pest management (IPM) are enhancing the effectiveness of nematode control. At the same time, stricter regulations governing chemical fumigants are accelerating the adoption of bio-based nematicide alternatives. Continuous product innovations, supportive government policies, and strategic investments by leading agrochemical companies are also expected to contribute significantly to market expansion.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=193252005

Soil Dressing Emerges as a Significant Application Method

By mode of application, the soil dressing segment is estimated to account for a significant share of the nematicides market. The method is widely used because it directly targets nematodes present in the soil, where crop damage typically begins. Soil dressing enables uniform distribution of nematicides, facilitating better penetration into the root zone and providing prolonged protection against nematode infestations.

Farmers across major agricultural regions increasingly prefer soil dressing as it supports root establishment, improves nutrient uptake, and contributes to higher yields in crops such as vegetables, cereals, and pulses. The technique is particularly valuable in intensive farming systems where nematode pressure is high and consistent crop protection is essential.

Technological advancements in formulations, including granular and liquid soil-applied products, have further improved the convenience, safety, and efficiency of soil dressing applications. As the agricultural industry continues to focus on sustainable crop protection, the method is expected to remain important by enabling precise application, reducing product wastage, and improving nematode management.

Fruits & Vegetables Segment Expected to Dominate by Crop Type

By crop type, the fruits and vegetables segment is estimated to hold the largest share of the nematicides market. The segment’s dominance is supported by the high economic value of horticultural crops and their susceptibility to nematode infestations. Root-knot and cyst nematodes can significantly affect crops such as tomatoes, cucumbers, potatoes, carrots, and citrus, resulting in substantial yield and quality losses.

Growing consumer demand for fresh and residue-free produce is encouraging farmers to adopt both chemical and biological nematicides to protect crop productivity while meeting evolving market standards. Intensive cultivation practices and year-round production cycles in horticulture further increase nematode pressure, making effective nematode management essential.

In Europe, North America, and Asia Pacific, the expansion of large-scale fruit and vegetable production, particularly under protected cultivation systems, is supporting the adoption of advanced nematicide formulations. The increasing use of seed-applied and bio-based products is further strengthening the position of the fruits and vegetables segment in the global nematicides market.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=193252005

Europe Estimated to Lead the Global Nematicides Market

Europe is estimated to lead the global nematicides market, supported by extensive cultivation of high-value crops and the growing need to manage plant-parasitic nematodes. Crops including soybeans, corn, cotton, and vegetables are particularly vulnerable to nematode infestations, with root-knot, soybean cyst, and lesion nematodes contributing to significant agricultural losses.

North America is also witnessing strong demand for nematicides, driven by large-scale and mechanized farming systems across the US and Canada. Farmers are increasingly focused on maximizing productivity and protecting profitability amid pressures associated with limited arable land. The rapid adoption of seed-applied nematicides and the integration of nematode management with precision agriculture are further supporting regional market growth.

Seed treatments are gaining traction in North America as they offer targeted and cost-effective protection throughout the growing season while aligning with modern sustainable farming practices. Product innovation and new product launches by leading agrochemical companies, combined with research support from land-grant universities and government-backed extension programs, have contributed to greater awareness and adoption of advanced nematicide solutions.

The region also benefits from a regulatory environment that supports the development and introduction of biological and bio-based nematicides alongside conventional chemical products. Rising consumer demand for residue-free produce and increasing environmental safety requirements are further encouraging the transition toward more sustainable nematode management solutions.

Leading Nematicides Companies

The report profiles several prominent companies operating in the global nematicides market, including BASF SE (Germany), Bayer AG (Germany), UPL (India), Corteva (US), Novonesis Group (Denmark), FMC Corporation (US), Nufarm (Australia), Syngenta (Switzerland), American Vanguard Corporation (US), and Sumitomo Chemicals (Japan). These companies are focusing on product innovation, strategic investments, technological advancements, and sustainable crop protection solutions to strengthen their market positions.

With increasing pressure to minimize crop losses, improve agricultural productivity, and adopt environmentally responsible crop protection practices, the global nematicides market is expected to witness robust growth through 2031. The continued development of biological solutions, advanced formulations, seed-applied technologies, and precision-based application methods is likely to create new opportunities for market participants in the coming years.

Specialty Fertilizers Market Report: Regional Analysis and Growth Opportunities

marketsandmarkets logo

The global specialty fertilizer market is projected to grow from USD 32.29 billion in 2026 to USD 45.49 billion by 2031, registering a CAGR of 7.1% during the forecast period.

The global specialty fertilizer market is poised for robust growth as agricultural producers increasingly adopt advanced crop nutrition solutions to improve productivity, optimize nutrient-use efficiency, and support sustainable farming practices. The growing demand for high-quality agricultural output, coupled with advancements in precision agriculture and modern irrigation technologies, continues to accelerate market expansion across developed and emerging economies.

Specialty fertilizers—including controlled-release fertilizers, water-soluble fertilizers, micronutrients, and fertigation products—are becoming integral components of modern farming systems. Farmers, agribusinesses, and commercial growers are increasingly utilizing these solutions to maximize crop yields while minimizing nutrient losses and environmental impact.

The rising awareness of balanced plant nutrition, increasing recognition of soil nutrient deficiencies, and expanding implementation of data-driven nutrient management practices are strengthening demand across major agricultural regions, particularly Asia Pacific, North America, and Europe. In addition, supportive government initiatives, expanding distribution networks, greenhouse cultivation, and continued investments in sustainable agriculture are creating favorable conditions for market growth worldwide.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=57479139

Micronutrients Segment Maintains Strong Market Position

Based on technology, the micronutrients segment continues to account for a significant share of the specialty fertilizer market. As intensive farming practices and continuous cropping reduce essential nutrients in agricultural soils, growers are increasingly incorporating micronutrient fertilizers into their crop nutrition programs.

Essential nutrients such as zinc, iron, boron, manganese, copper, and molybdenum play vital roles in photosynthesis, enzyme activation, and nutrient metabolism, directly influencing crop productivity and quality. Demand is particularly strong in fruits, vegetables, oilseeds, pulses, and horticultural crops, where micronutrient deficiencies can significantly affect both yield and market value.

The increasing availability of chelated micronutrient formulations, wider adoption of foliar applications and fertigation systems, and growing awareness of balanced fertilization practices are further supporting segment growth. Government-led soil health initiatives and nutrient management programs continue to encourage farmers to adopt micronutrient-based specialty fertilizers.

Fruits & Vegetables Segment Expected to Register Strong Growth

By crop type, the fruits & vegetables segment is projected to witness significant growth throughout the forecast period. Rising global consumption of fresh produce and increasing demand for premium-quality fruits and vegetables are encouraging growers to invest in advanced fertilizer technologies that enhance crop performance.

Specialty fertilizers enable precise nutrient delivery throughout the crop growth cycle, helping improve fruit size, color, nutritional value, shelf life, and overall quality while reducing nutrient wastage. Water-soluble fertilizers, controlled-release fertilizers, micronutrients, and fertigation products have become essential tools for high-value horticultural production.

The expansion of greenhouse cultivation, protected agriculture, and export-oriented horticulture—particularly across Asia Pacific, Europe, and North America—is expected to further strengthen demand for specialty fertilizers in this segment.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=57479139

Europe Emerges as a Key Regional Market

Europe represents one of the leading regional markets for specialty fertilizers, supported by advanced farming practices, stringent environmental regulations, and widespread adoption of precision nutrient management technologies.

Farmers across Germany, France, Italy, Spain, and the United Kingdom are increasingly utilizing water-soluble fertilizers, controlled-release fertilizers, and micronutrient products to enhance crop productivity while improving fertilizer-use efficiency and reducing environmental impact.

The region’s emphasis on sustainable agriculture, soil health improvement, greenhouse cultivation, and production of high-value crops continues to drive adoption of innovative specialty fertilizer solutions across cereals, fruits, vegetables, horticultural crops, and specialty crop applications. Continued investments in agricultural innovation and precision farming technologies are expected to reinforce Europe’s leadership position in the global specialty fertilizer market over the coming years.

Leading Specialty Fertilizers Companies:

The specialty fertilizer market features a competitive landscape with the presence of several global and regional manufacturers focused on innovation, product development, strategic partnerships, and sustainable agricultural solutions. Key market participants include Nutrien Ltd. (Canada), Yara International ASA (Norway), ICL Group Ltd. (Israel), K+S Aktiengesellschaft (Germany), SQM S.A. (Chile), EuroChem Group (Switzerland), CF Industries Holdings, Inc. (US), Nufarm Limited (Australia), The Mosaic Company (US), OCI Global (Netherlands), OCP Group (Morocco), Kingenta Ecological Engineering Group Co., Ltd. (China), Coromandel International Limited (India), Deepak Fertilisers and Petrochemicals Corporation Limited (India), Zuari Agro Chemicals Limited (India), Kugler Company (US), Haifa Group (Israel), COMPO EXPERT GmbH (Germany), Wilbur-Ellis Holdings, Inc. (US), Valagro S.p.A. (Italy), BRANDT, Inc. (US), and AgroLiquid (US).

As global agriculture increasingly prioritizes sustainability, resource efficiency, and precision crop management, specialty fertilizers are expected to play an increasingly critical role in supporting higher agricultural productivity and long-term food security. Continued technological innovation, favorable government policies, and growing awareness of balanced crop nutrition are anticipated to drive sustained market growth through 2031.

Biostimulants Market Forecast: Regional Analysis and Revenue Opportunities

marketsandmarkets logo

The global biostimulants market is projected to grow from USD 4.97 billion in 2026 to USD 8.77 billion by 2031, registering a compound annual growth rate (CAGR) of 12.0% during the forecast period. The market is experiencing robust expansion as farmers, agribusinesses, and commercial growers increasingly adopt biostimulants to improve crop productivity while promoting environmentally sustainable agricultural practices.

The growing emphasis on improving nutrient efficiency, enhancing plant resilience to environmental stresses, and maintaining long-term soil health has significantly accelerated the adoption of biostimulants worldwide. Europe and North America continue to lead market adoption, particularly in cereal, horticultural, and high-value crop production, where biostimulants play a critical role in improving crop performance and yield stability.

The rising demand for microbial-based products, seaweed extracts, amino acid formulations, and other natural biostimulant solutions is further strengthening market growth. In addition, advancements in precision agriculture, digital farming technologies, agritech platforms, and expanding distribution networks are making these products more accessible to both commercial and smallholder farmers across global agricultural markets.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=1081

Liquid Form Segment Dominates the Market

Among various product forms, the liquid segment continues to account for a significant share of the global biostimulants market. Liquid biostimulants are widely preferred due to their ease of application, uniform crop coverage, and compatibility with foliar spraying, fertigation, and seed treatment systems.

These formulations—including microbial suspensions, seaweed extracts, amino acid blends, and nutrient-based solutions—offer rapid absorption, efficient nutrient delivery, and enhanced protection against abiotic stresses. Their ability to integrate seamlessly with existing crop nutrition and crop protection programs has further increased their popularity among growers seeking convenient, ready-to-use solutions for improving crop performance.

Cereals & Grains Segment Registers Strong Growth

Based on crop type, the cereals & grains segment is expected to witness substantial growth throughout the forecast period. Extensive cultivation of staple crops such as wheat, rice, and maize continues to drive demand for biostimulants that enhance nutrient uptake, stimulate root development, and improve tolerance to drought, heat, and salinity.

Growing global demand for food grains, supportive government initiatives promoting sustainable agriculture, and increasing farmer awareness regarding yield optimization are contributing significantly to segment growth. The widespread application of microbial, seaweed-based, and amino acid biostimulants is helping improve crop productivity while supporting sustainable farming objectives.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=1081

North America Holds a Significant Market Share

North America represents a significant share of the global biostimulants market, supported by advanced farming practices, increasing investment in biological crop inputs, and widespread adoption of sustainable agriculture technologies.

Farmers across the United States and Canada are increasingly utilizing biostimulants to improve nutrient use efficiency, strengthen plant resilience under environmental stress, and preserve soil fertility while reducing dependence on conventional agrochemicals. Favorable regulatory developments, continued research and innovation, and the expansion of high-value crop cultivation—including fruits, vegetables, and specialty crops—are expected to further support regional market growth.

Leading Biostimulants Companies:

Major companies operating in the global biostimulants market include UPL Limited (India), FMC Corporation (US), Corteva Agriscience (US), Sumitomo Chemical Co., Ltd. (Japan), Nufarm Limited (Australia), Novonesis (Denmark), BASF SE (Germany), Bayer AG (Germany), PI Industries Ltd. (India), T. Stanes & Company Limited (India), J.M. Huber Corporation (US), Gowan Company (US), Koppert Biological Systems (Netherlands), Acadian Seaplants Limited (Canada), Qingdao Seawin Biotech Group Co., Ltd. (China), OMEX Agriculture (UK), Seipasa S.A. (Spain), Aminocore (South Africa), and Cascadia Seaweed Corp. (Canada).

Biofertilizers Market Forecast 2026–2031: Emerging Technologies and Growth Prospects

marketsandmarkets logo

The global biofertilizer market is expected to grow from USD 4.08 billion in 2026 to USD 6.94 billion by 2031, registering a compound annual growth rate (CAGR) of 11.2% during the forecast period. The market is experiencing strong momentum as agricultural producers increasingly adopt sustainable nutrient management practices to enhance soil fertility, improve crop productivity, and reduce dependence on synthetic fertilizers.

The transition toward environmentally responsible agriculture, coupled with growing concerns over soil degradation, declining nutrient-use efficiency, and environmental pollution, continues to accelerate the adoption of microbial-based fertilizers worldwide. Biofertilizers are gaining widespread acceptance for their ability to improve nutrient availability, strengthen root development, enhance crop quality, and support long-term soil health across cereals, pulses, oilseeds, fruits, vegetables, horticultural, and floricultural crops.

The rising consumption of organic food, increasing emphasis on residue-free farming and food production, and expanding farmer awareness of sustainable agricultural practices are further supporting market growth. In addition, continuous investments in microbial strain discovery, formulation technologies, and large-scale microbial production are enabling the commercialization of innovative, cost-effective biofertilizer products designed to meet evolving agricultural requirements.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=856

Bacterial Biofertilizers Lead the Market by Source

Among all source categories, bacterial biofertilizers account for the largest share of the global market due to their proven effectiveness in nitrogen fixation, phosphate solubilization, nutrient mobilization, and enhancement of soil biological activity. Beneficial microorganisms including Rhizobium, Azotobacter, Azospirillum, Bacillus, and Pseudomonas play a vital role in improving nutrient availability, stimulating root growth, and increasing crop yields while minimizing dependence on chemical fertilizers.

Their broad compatibility with cereals, grains, pulses, oilseeds, fruits, vegetables, and horticultural crops has reinforced their market leadership. Ongoing advancements in microbial strain development, multifunctional bio-inoculants, liquid formulations, and customized bacterial solutions tailored to specific cropping systems continue to strengthen the growth outlook for this segment.

Phosphate-Solubilizing and Mobilizing Biofertilizers Dominate by Type

By type, phosphate-solubilizing and mobilizing biofertilizers represent the largest market segment due to their critical role in improving phosphorus availability and nutrient uptake. Utilizing beneficial microorganisms such as Bacillus, Pseudomonas, Aspergillus, and Penicillium, these biofertilizers convert insoluble phosphorus into plant-available forms, enhancing crop productivity and soil fertility.

Growing concerns regarding phosphorus scarcity, rising costs of synthetic phosphate fertilizers, and declining fertilizer-use efficiency are encouraging farmers to adopt biological phosphorus solutions. Furthermore, innovations in microbial consortia, liquid formulations, and advanced microbial stabilization technologies are improving product performance and field effectiveness, supporting continued expansion of this segment.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=856

Liquid Biofertilizers Maintain Market Leadership by Form

Liquid biofertilizers continue to hold the largest share of the global market owing to their superior microbial concentration, extended shelf life, ease of application, and enhanced crop performance compared with conventional carrier-based formulations.

The increasing adoption of precision agriculture, conservation farming, drip irrigation, and efficient nutrient management practices has significantly boosted demand for liquid formulations across a wide range of agricultural crops. Technological advances in microbial preservation, formulation stability, and controlled-release biological systems are further accelerating product commercialization. Supportive government initiatives promoting sustainable agriculture and reducing chemical fertilizer usage are expected to sustain long-term growth in this segment.

Europe Expected to Register the Fastest Growth

Europe is projected to record the highest CAGR in the global biofertilizer market throughout the forecast period. Strong regulatory support for sustainable agriculture, strict environmental policies, and limitations on synthetic fertilizer usage are driving rapid adoption of biological crop nutrition solutions across the region.

The expansion of organic farming and regenerative agriculture in countries including Spain, Italy, France, Germany, and the Netherlands is creating substantial opportunities for biofertilizer manufacturers. In addition, European Union initiatives focused on reducing chemical inputs and promoting biological soil amendments are expected to further strengthen market growth.

Increasing consumer demand for organic and residue-free food products, combined with continued investments in microbial technologies and precision agriculture, is expected to reinforce Europe’s leadership in sustainable agricultural innovation.

Leading Biofertilizers Companies:

The report profiles several prominent companies operating in the global biofertilizer market, including Novonesis (Denmark), UPL Limited (India), Syngenta AG (Switzerland), T. Stanes & Company (India), Lallemand Inc. (Canada), Rizobacter (Argentina), Gujarat State Fertilizers and Chemicals Ltd. (India), Madras Fertilizers Limited (India), IPL Biologicals (India), Koppert Biological Systems (Netherlands), Corteva Agriscience (United States), Kan Biosys (India), Mapleton Agri Biotech Pvt. Ltd. (India), and Seipasa S.A. (Spain).

US Aquafeed Industry Report: Emerging Trends & Market Forecast

marketsandmarkets logo

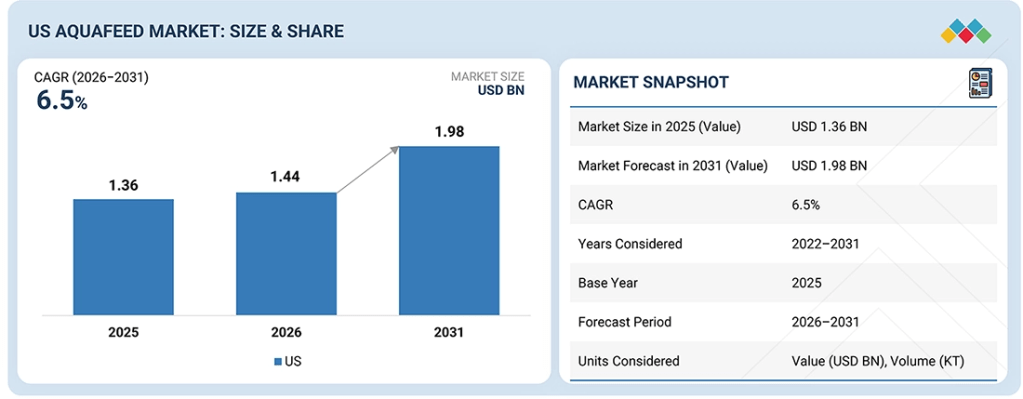
The US aquafeed market is projected to grow from USD 1.44 billion in 2026 to reach USD 1.98 billion by 2031, at a Compound Annual Growth Rate (CAGR) of 6.5% during the forecast period. The US aquafeed market is growing as demand for seafood increases and commercial fish farming grows. Farmers seek faster growth and higher survival rates for aquatic species. They prioritize efficient feed conversion and consistent production. Intensive farming systems rely on balanced formulated feed to support daily performance and minimize losses. Species like salmon, trout, catfish, and tilapia depend entirely on compound aquafeed for nutrition. Producers also emphasize feed efficiency and cost management. This fuels demand for protein-rich ingredients and functional additives. Aquaculture producers prefer diets that are scientifically validated and easy to manage. Greater focus is also placed on fish health, water quality, and sustainable farming practices. Many farms now use automated feeding systems, which facilitate the use of standard dry pellet feed. Feed directly impacts production volume, fish quality, and farm profitability. Therefore, aquafeed remains a key input in US aquaculture, maintaining steady demand across the market.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=3345366

Amino acids under the additives segment of the US aquafeed market are estimated to hold the largest share in the US aquafeed market during the forecast period.

In the US aquafeed market, amino acid additives hold the largest share because they directly support faster growth, better feed efficiency, and improved protein utilization in fish and shrimp. Aquaculture producers focus on performance, uniform growth, and high survival rates. Essential amino acids such as lysine, methionine, and threonine help meet specific nutritional needs at different growth stages. They also promote muscle development and overall health. Since these benefits are clear and measurable, feed manufacturers regularly include amino acids, keeping this segment at the top.

The grower phase of the lifecycle is estimated to be the fastest-growing during the forecast period in the US aquafeed market.

The grower stage is expected to experience the fastest growth in the US aquafeed market during the forecast period. This stage lasts longer than both the hatchery and starter phases, making it essential for fish development since they gain most of their body weight during this time. To support consistent growth and ensure efficient feed conversion, farmers use large amounts of feed. As US aquaculture farms aim to boost output and shorten time-to-market, there is increased focus on the quality of grower feed. Additionally, stocking density is higher during this stage, further increasing total feed usage. Since feed costs are among the highest operating expenses for farms, producers are investing in well-balanced grower diets that promote weight gain and help protect profit margins. Due to the longer duration of this stage and the higher feed intake, the grower segment is expected to see the most significant growth in the US aquafeed market throughout the forecast period.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=3345366

Crustaceans under the species segment will register the highest CAGR during the forecast period in the US aquafeed market.

The crustacean segment in the US aquafeed market is expanding as shrimp farming increases. The USDA’s 2023 Census of Aquaculture reports 51 saltwater shrimp farms in the US, mostly in Florida and Texas, with seven inland farms in Iowa, Kentucky, Minnesota, and Missouri. Shrimp makes up about 38% of total seafood consumption in the country. The average American consumes around 5.5 pounds per year, totaling more than 1.5 billion pounds annually. However, the US imports roughly 90% of its shrimp, which opens significant opportunities for domestic production growth.

As inland and coastal shrimp farms expand, feed demand rises because shrimp rely entirely on formulated aquafeed for growth and survival. Many new farms use closed-loop Recirculating Aquaculture Systems to enhance efficiency and minimize water loss. With high consumer demand, heavy import dependence, and growing domestic production, the crustaceans’ segment is expected to grow at a faster pace in the US aquafeed market during the forecast period.

Leading US Aquafeed Companies:

The report highlights key players such as Cargill (US), ADM (US), dsm firmenich (Switzerland), Nutreco (Netherlands), Alltech (US), Purina Animal Nutrition LLC (US), Adisseo (France), Kemin Industries, Inc. (US), Darling Ingredients (US), Rangen LLC (US), The Scoular Company (US), Novus International (US), Norel Animal Nutrition (Spain), Kent Nutrition Group (US), and Beneo (Germany), among others.

Crop Protection Chemicals Market Insights: Industry Analysis & Growth Opportunities

marketsandmarkets logo

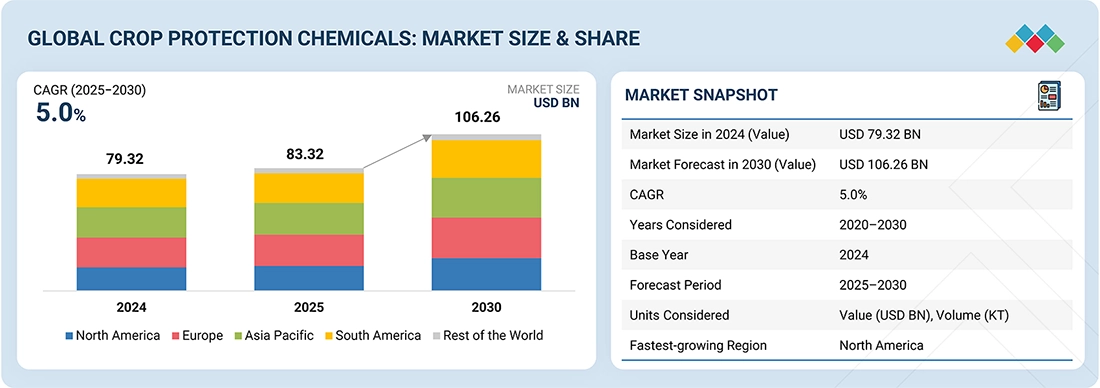
The crop protection chemical market is estimated at USD 83.32 billion in 2025 and is projected to reach USD 106.26 billion by 2030, at a CAGR of 5.0% from 2025 to 2030. The advancement of global trade in agricultural commodities has created a lot of pressure upon the farmer to meet stringent quality, appearance, and phytosanitary standards that would invariably increase the use of crop protection products. Agricultural labor shortages in several parts of the world have accelerated the trend toward chemical solutions as cheaper and easily scalable alternatives to manual weed and pest control. The organized retail, contract farming, and food processing industries are creating more and stronger demand for uniform, residue-compliant produce, indirectly facilitating continued adoption of crop protection chemicals across the global agriculture value chain.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=380

The synthetic crop protection chemicals segment holds the highest market share, by origin

Synthetic products hold the highest share in the origin segment of the crop protection chemical market, primarily due to their proven efficacy, broad-spectrum activity, and consistent performance across diverse crops and agro-climatic conditions. In particular, they are able to deliver both quick and reliable control levels of weeds, pests, and diseases. Thus, synthetic herbicides, fungicides, and insecticides are considered the best options in agro-commercial and large-scale farming systems. The highly standardized manufacturing processes, extended shelf life, and compatibility with modern applications provide features that favor developed countries and commercial farms for their usage. In addition, on the entire hectare basis of coverage, synthetic chemistry typically has a more economical response to the costs involved, which is important for farmers who want to get as much yield as possible while controlling input costs.

The soil treatment segment holds a significant share in the market, by mode of application

Soil treatment holds a significant share in the mode of application segment, as it combats key problems caused by soil-borne pathogens, nematodes, and root diseases that impact crop establishment and yield. The use of crop protection chemicals in soil drenching, seed bed treatment, and root-zone application supports better microbial colonization and long-term protection. Organic practices that enhance soil health, improve nutrient uptake, and minimize early-stage crop losses have found wide acceptance in horticulture, row crops, and protected cultivation systems.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=380

Based on region, Asia Pacific holds a large share in the crop protection chemical market.

The Asia Pacific region holds a significant share of the crop protection chemical market due to its vast agricultural base, high cropping intensity, and strong reliance on agriculture for food security and rural livelihoods. Important staple crops, mainly rice, wheat, maize, and pulses, which are produced largely on a global scale, do require regular management pertaining to weeds, pests, and diseases. Smallholder-style dominant farming systems, varied cropping cycles, and year-round cultivation in many countries increase the frequency of crop protection chemical use. Besides, rapid population increases and rising food consumption drive governments and farmers to focus on yield stability and loss prevention. Enhancing access to crop protection inputs, strengthening distribution networks, and increasing adoption of modern farming practices tend to offer great demand across key markets, including China, India, Southeast Asia, and Australia.

Leading Crop Protection Chemicals Companies:

The report profiles key players such as BASF SE (Germany), Bayer AG (Germany), FMC Corporation (US), Syngenta Group (Switzerland), Corteva (US), UPL (India), Nufarm (Australia), Sumitomo Chemical Co., Ltd (Japan), Albaugh LLC (US), Koppert (Netherlands), Gowan Company (US), American Vanguard Corporation (US), Kumiai Chemical Industry Co., Ltd (Japan), PI Industries (India), and BioFirst Group (Belgium).

Agriculture Utility Adjuvants Market Trends, Growth Factors, and Future Opportunities

marketsandmarkets logo

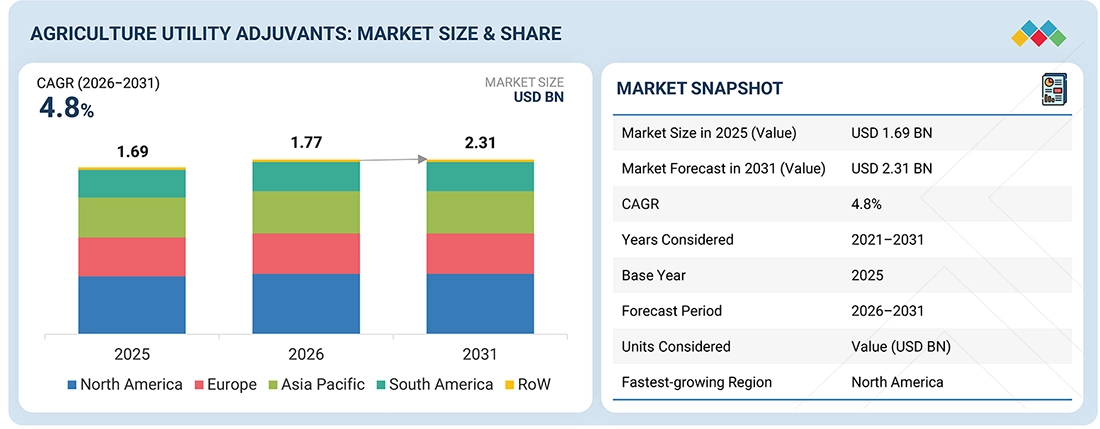
The agriculture utility adjuvants market is projected to reach USD 2.31 billion by 2031 from USD 1.77 billion in 2026, at a CAGR of 4.8% from 2026 to 2031. The global utility adjuvants market is experiencing rising demand due to increased attention from farmers on optimizing the quality of spray water, tank mixes, and the effectiveness of crop protection agents. Stricter government regulations concerning environmental safety, spray precision, and pesticide use have further supported market growth. The adoption of precision farming techniques has also created a need for more reliable spray solutions. Additionally, manufacturers are increasingly emphasizing the use of water conditioners, buffering agents, anti-foaming agents, and compatibility enhancers to improve the physical and chemical stability of spray mixtures. Utility adjuvants play a vital role in neutralizing hard water minerals, maintaining pH levels, controlling foam formation, and ensuring the compatibility of multiple agrochemicals in the same spray tank. Rising farmer interest in effective application methods and reducing chemical wastage is also driving the development of advanced utility adjuvants to boost operational efficiency and preserve active ingredients. As modern agriculture continues to evolve toward higher productivity and sustainability through precision practices, the utility adjuvants market is expected to remain a key part of the global crop protection industry.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=131568926

The emulsifiable concentrates segment holds a significant market share in the formulation segment.

Emulsifiable concentrates (EC) also hold a significant market share in the formulation segment of the utility adjuvants market because of their excellent compatibility and ability to blend with crop protection products. This formulation type allows for the emulsification of oil-soluble functional ingredients to mix with water in the spray tank, ensuring an even distribution of active and performance-enhancing ingredients. The capacity to maintain solution stability across varying water qualities and conditions makes this formulation type suitable for large-scale agricultural spraying activities.

Furthermore, using emulsifiable concentrates improves the functional efficiency of utility modifiers, which in turn enhances mix qualities, prevents separation, and makes product application easier through spraying. Additionally, the product’s versatility, including herbicides, fungicides, and insecticides, boosts its market viability. Moreover, the growing demand for versatile, ready-to-mix liquid formulations that work in diverse climates increases the dominance of the emulsifiable concentrates segment in the formulation market.

In the application segment, herbicides is the fastest-growing segment in the global agricultural adjuvants market.

The global agricultural utility adjuvants market is growing fastest in the herbicide application segment. The increased adoption of herbicides to combat rising weed resistance issues, along with the expanding use of conservation tillage methods, drives this growth. Spraying adjuvants improve herbicide effectiveness by enhancing spray coverage, droplet retention, cuticle penetration, and rainfastness, leading to better active ingredient performance. The agriculture industry needs utility adjuvants to meet the growing demand driven by precision spraying technology and tank-mix applications for herbicides. Dual pressures from regulations demanding better pesticide practices and environmental protection motivate farmers to use adjuvants for effective weed control at lower chemical application levels.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=131568926

Based on region, Europe holds a significant share in the global agricultural utility adjuvants market.

Based on the region-wise segmentation, Europe has emerged as a prominent player in the global utility adjuvants market due to its strong regulatory environment and focus on sustainable agriculture. The region has implemented strict policies regarding pesticide use, drift prevention, water conservation, and environmental safety. These regulations have increased the demand for high-quality water conditioners, buffering agents, compatibility agents, and anti-foaming agents to ensure the responsible use of agrochemicals. Additionally, the adoption of precision agriculture tools, such as variable-rate sprayers and digital spray-monitoring devices, is very high in Europe. These tools require well-conditioned and stable spray solutions to perform optimally, which also drives demand for utility adjuvants. Furthermore, Europe’s well-established agrochemical industry, ongoing R&D efforts in formulation sciences, and the growing preference for bio-based and eco-friendly products further reinforce its position in the global market. Lastly, government initiatives supporting the utility adjuvant market amid current market conditions are expected to continue boosting the industry.

The extensive agricultural landscapes of countries such as France, Germany, Spain, and Italy have created opportunities for farmers to use more crop protection products and tank mix adjuvants. The widespread adoption of precision farming and crop management practices has greatly increased the demand for tank mix adjuvants. Additionally, the growing preference for bio-based, environmentally friendly products has supported the sustainable use of pesticides and crop protection solutions. The rapid innovation in specialty chemicals and agrochemicals has positioned Europe as a leading region in the tank mix adjuvants market.

Leading Agriculture Utility Adjuvants Companies:

The report profiles key players such as BASF SE, Corteva Agriscience, Croda International Plc, Evonik Industries AG, Solvay SA, Nufarm Ltd., Dow Inc., Clariant AG, Huntsman Corporation, Helena Agri-Enterprises LLC, Wilbur-Ellis Company LLC, Stepan Company, Brandt Consolidated Inc., Akzo Nobel N.V., and Adjuvant Plus Inc.

Microirrigation Systems Market: Growth Drivers and Competitive Landscape

marketsandmarkets logo

The microirrigation systems market is projected to grow from USD 13.50 billion in 2025 to reach USD 21.56 billion by 2030, at a compound annual growth rate (CAGR) of 9.8% during the forecast period. The microirrigation systems market is expanding due to ongoing improvements in irrigation hardware, software, and services. Modern microirrigation systems now often include automation and smart control technologies. This allows for precise scheduling, real-time flow regulation, and consistent water distribution. These features enable farmers to optimize when and how much they irrigate, significantly reducing water waste, energy use, and reliance on labor while boosting efficiency. At the same time, advances in sensor technology, remote monitoring, and data analysis are changing irrigation from a reactive task into a proactive, data-driven process. Monitoring soil moisture, weather conditions, evaporation rates, and crop-specific water needs in real time enables growers to adjust irrigation strategies based on current field conditions. This can improve crop health, ensure more consistent yields, and increase resilience to climate change and water shortages.

Furthermore, combining fertigation systems with digital irrigation platforms enables precise nutrient delivery with water. This improves the effectiveness of fertilizers and reduces runoff, benefiting the environment. Cloud-based platforms, mobile apps, and IoT connections make these systems easier to use by providing valuable insights, alerts, and performance tracking. Together, these innovations are enhancing returns for farmers and speeding up the adoption of microirrigation systems, particularly in high-value crops, greenhouses, and areas facing water scarcity. This trend supports long-term market growth.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=566

By type, the sprinkler irrigation segment is projected to be fastest growing segment.

The micro sprinkler segment is expected to be the fastest-growing within the microirrigation systems market during the forecast period, driven by its ability to balance precision, coverage, and operational efficiency. Micro sprinklers deliver uniform water distribution across fields, orchards, and gardens, and can be strategically positioned to irrigate specific zones or individual plants. This targeted coverage ensures that each plant receives adequate moisture, reducing both under- and over-irrigation and supporting healthier plant growth.

Compared with conventional sprinkler systems, micro sprinklers operate at lower pressures and flow rates, which significantly reduces energy consumption for pumping and lowers overall operating costs. They are particularly well-suited for orchards, vineyards, nurseries, and plantation crops, where wider root zones and canopy coverage are required. In addition, micro sprinklers perform well on uneven terrain and in soils with lower infiltration rates, offering greater flexibility across varied agronomic conditions. These advantages, combined with rising emphasis on water efficiency and energy savings, are accelerating the adoption of micro sprinkler systems and positioning the segment for strong growth over the forecast period.

By end user, industrial user is estimated to be the fastest-growing segment during the review period.

The industrial user segment is expected to be the fastest-growing part of the microirrigation systems market during this review period. This growth is driven by a growing focus on environmental sustainability, operational efficiency, and regulatory requirements. Industrial users, which include commercial agribusinesses, plantations, food processors with their own farms, and large institutional growers, are increasingly adopting microirrigation technologies to practice eco-friendly water management. These systems help reduce water waste, reduce fertilizer and pesticide runoff, and improve resource use. This makes them an attractive option for organizations looking to lower their environmental impact while keeping up productivity.

Technological progress is also boosting adoption among industrial users. Modern microirrigation systems can be monitored and controlled remotely through IoT-enabled platforms, mobile apps, and computer dashboards. This allows for real-time changes to irrigation schedules, flow rates, and fertigation settings. Remote access is especially useful for businesses managing large or spread-out operations. It adds convenience, improves decision-making, and lowers the need for on-site labor. As sustainability goals, cost-cutting, and digital transformation become vital to industrial operations, demand for new microirrigation solutions is likely to accelerate further.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=566

Asia Pacific is estimated to be the fastest-growing region during the study period.

The Asia Pacific region is increasingly affected by irregular rainfall patterns, prolonged droughts, and frequent heat waves, all of which are intensifying pressure on agricultural water management. Under these volatile climatic conditions, microirrigation systems play a critical role in delivering regulated and efficient water distribution, helping farms maintain productivity despite reduced or unpredictable water availability. By supplying water directly to the root zone in controlled quantities, microirrigation reduces water stress on crops and enhances their resilience to extreme weather events.

Microirrigation systems also allow farmers to fine-tune irrigation schedules and application volumes based on specific crop requirements, soil conditions, and growth stages. This level of precision enables crops to better endure and adapt to changing climatic conditions, improving survival rates and yield stability. In addition, irrigation water in some regions may contain high levels of salts, heavy metals, or other contaminants, which can negatively affect soil health and crop productivity. To address this, microirrigation systems can be equipped with filtration and purification units that remove impurities before water reaches the plants. As a result, crops receive cleaner water, leading to improved plant health, higher yields, and reduced long-term damage to soil and crop systems caused by poor water quality.

Leading Microirrigation Systems Companies:

Eminent players operating in the microirrigation systems market are Jain Irrigation Systems Ltd. (India), The Toro Company (US), Netafim (Israel), Nelson Irrigation (US), Rain Bird Corporation (US), Finolex Plasson (India), Mahindra EPC Irrigation Limited (India), T-L Irrigation (US), Hunter Industries (US), Rivulis (Israel), Chinadrip irrigation Equipment co., Ltd. (China), Elgo Irrigation Ltd. (Israel), Antelco (Australia), Microjet (South Africa), and Irritec S.p.A. (Italy), among others.

Tank Mix Adjuvants Market Innovation, Technology, and Growth Outlook

marketsandmarkets logo

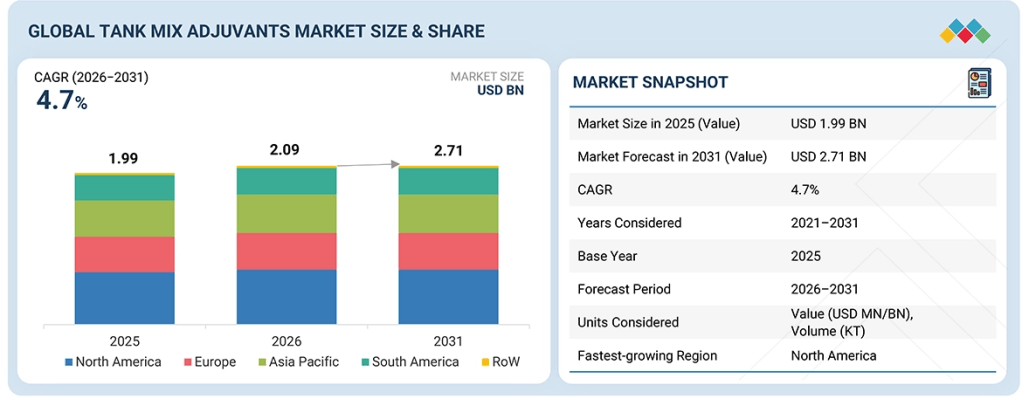
The tank mix adjuvants market is projected to reach USD 2.09 billion in 2026 and USD 2.71 billion by 2031, registering at a CAGR of 4.7% from 2026 to 2031. The tank mix adjuvants market is growing due to farmers’ increased focus on maximizing the efficiency of applied pesticides, stricter regulations by governments on spray drift and environmental safety, and the mounting adoption of precision agriculture. Manufacturers are increasingly relying on surfactants, oil concentrates, drift control agents, and water conditioners to maximize the efficiency of herbicides, insecticides, and fungicides in integrated crop management practices. The strong focus of farmers on maximizing the efficiency of the applied crop protection chemicals and the cost-effectiveness of the application encourages the adoption of innovative adjuvant technologies to maximize the efficiency of the application of herbicides, insecticides, and fungicides in integrated crop management practices.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=246363861

Emulsifiable concentrates segment is expected to hold a significant market share in 2031

Based on formulation type, the tank mix adjuvants market is dominated by the emulsifiable concentrates segment. The benefits of this formulation type include the capability to mix the oil-based active ingredients with water in the spray tank, leading to the formation of a consistent emulsion. This formulation increases the spreading, penetration, and absorption of active ingredients on the surface of the plants. This increases the suitability of the tank mix adjuvants for use in herbicide and insecticide tank mixes. This formulation type is also compatible with many crop protection products and nutrients. This increases the suitability of the formulation type for use in different crops and environmental conditions.

Herbicides segment is likely to be the fastest-growing in the tank mix adjuvants market from 2026 to 2031

Within the application segment, the herbicides segment emerges as the fastest-growing category in the global tank mix adjuvants market. This segment is primarily driven by the increasing incidence of herbicide-resistant weeds and the expansion of large-scale commercial farming. Tank mix adjuvants enhance herbicide efficacy by improving spray coverage, droplet size optimization, retention, and active ingredient penetration into plant tissues. The growing adoption of no-till and conservation agriculture practices further supports herbicide demand, accelerating adjuvant usage. Additionally, regulatory pressure to reduce overall pesticide loads encourages farmers to maximize herbicide performance through tank mix optimization, reinforcing this segment’s strong growth trajectory.

Request Sample Pages: https://www.marketsandmarkets.com/requestsampleNew.asp?id=246363861

Europe is expected to account for a significant share of the tank mix adjuvants market in 2031

Europe has emerged as a prominent region in the tank mix adjuvants market due to the implementation of stringent regulations that focus mainly on the sustainable use of pesticides and environmental protection. Regulations related to spray drift control, water protection, and residue management practices are expected to boost the demand for high-performance tank mix adjuvants. This, in turn, would lead to a high demand for high-performance surfactants, drift control agents, buffering agents, and water conditioning agents. The high agricultural landscape of France, Germany, Spain, and Italy has provided an opportunity for farmers to use more crop protection products and tank mix adjuvants. The high adoption rate of precision farming and crop management practices has significantly boosted the demand for tank mix adjuvants. The high demand for bio-based products that are environmentally friendly has aligned with the sustainable use of pesticides and crop protection products. The high rate of innovation in specialty chemicals and agrochemicals has made Europe a prominent player in the tank mix adjuvants market.

Leading Tank Mix Adjuvants Companies:

The report profiles key players such as BASF SE, Corteva Agriscience, Croda International Plc, Evonik Industries AG, Solvay SA, Nufarm Ltd., Dow Inc., Clariant AG, Huntsman Corporation, Helena Agri-Enterprises LLC, Wilbur-Ellis Company LLC, Stepan Company, Brandt Consolidated Inc., Akzo Nobel N.V., and Adjuvant Plus Inc.